Good morning. US equity futures are moderately higher, SPX +20pts, we’re set to open at 5937. USD is +0.04% at DXY 106.66. The precious metals are moderately higher, Gold +0.6% (printing $2676), with Silver +0.6% (printing $31.38). WTIC is +1.5% in the $70s.
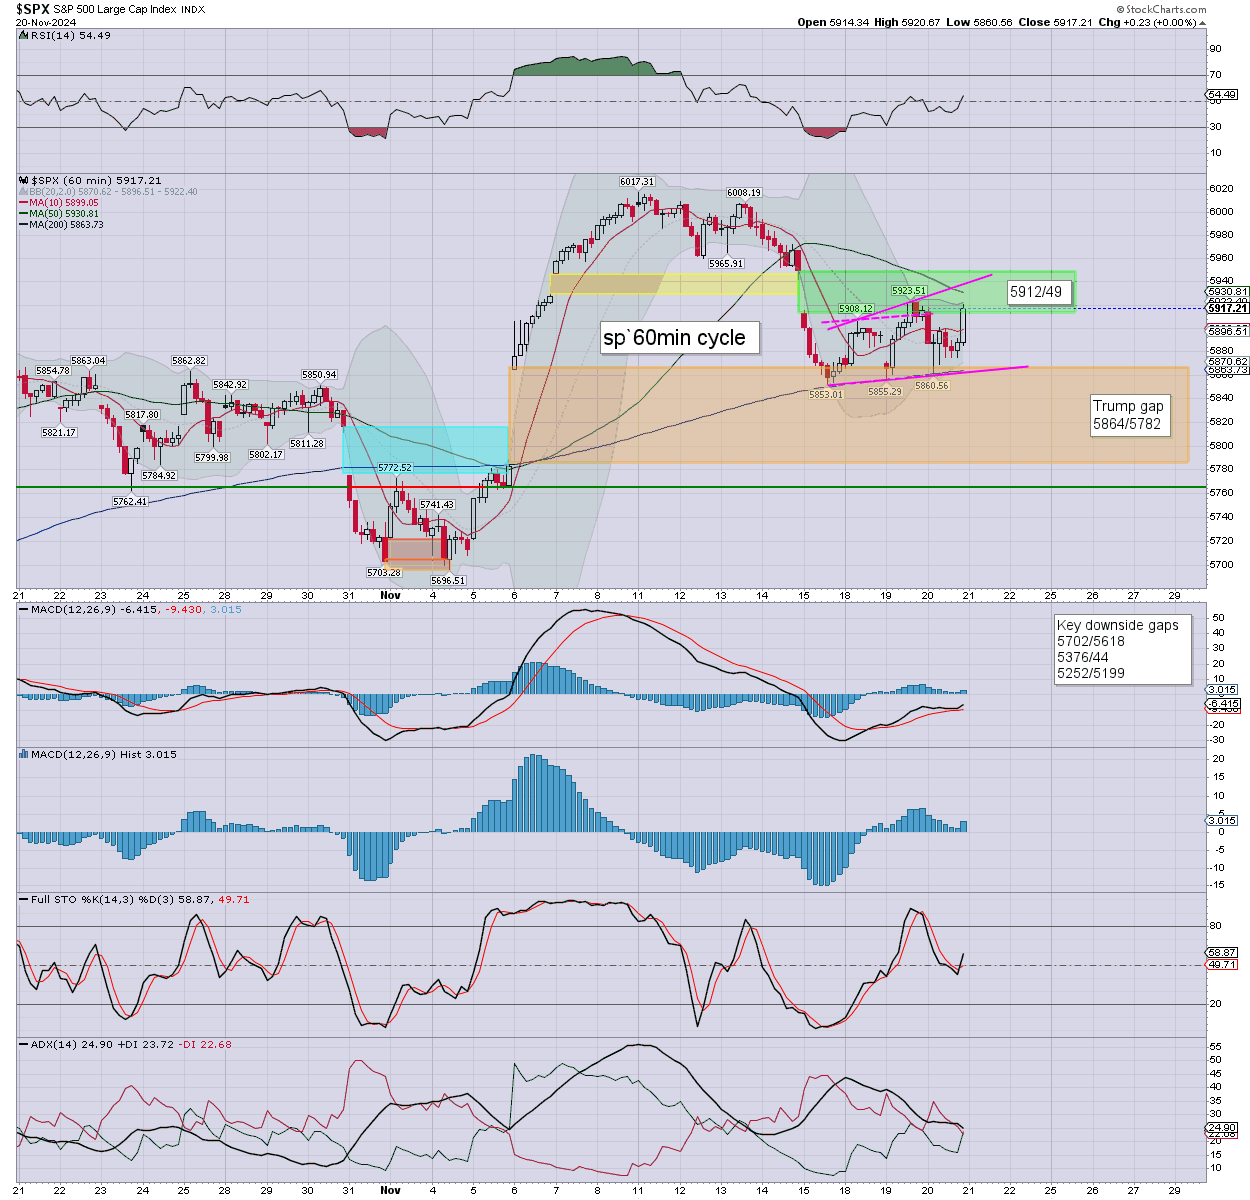
sp’60min
Summary
Yesterday saw early weakness on geo-pol news, but a recovery to settle almost precisely flat. S/t momentum settled marginally positive.
Overnight futures have been pretty subdued, we’re currently set to open +15/20pts. The s/t cyclical setup favours the bears. Structure is a valid bearish pennant unless >5940s.
The market will clearly be vulnerable to any further ‘spooky news’ that could occur at ANY time.
—
Early movers
AAPL +0.4%
AG +0.9%
ARKB +3.8%
BABA -2.8%
–
BJ +6.2%, EPS $1.18 vs 0.91est. Rev’ y/y +3.5% to $5.1bn inline. $1bn buyback
–
CCJ +1.7%, RBC $90
CLSK +4.0%
–
COIN +3.2%
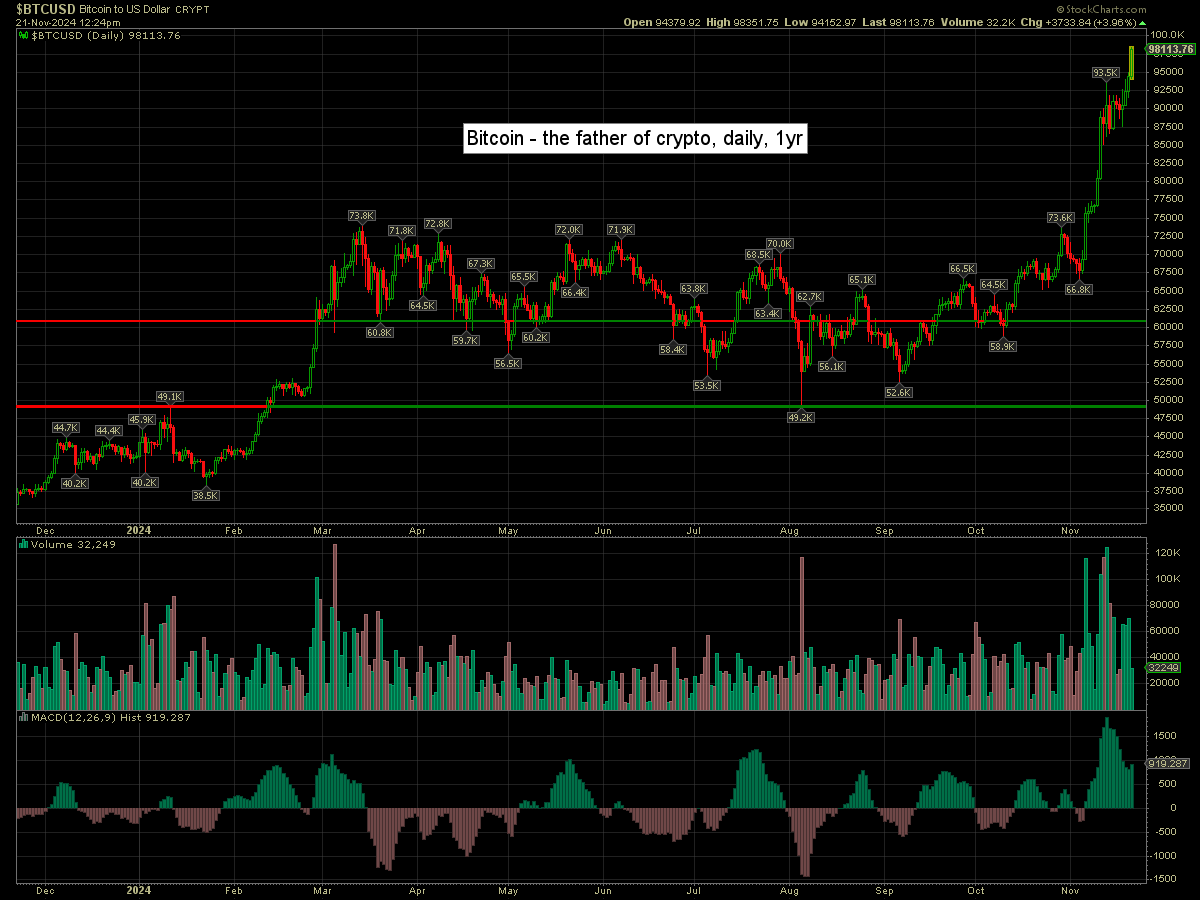
Bitcoin printed a new hist’ high of $98351, as giant psy’ $100K is set to be challenged.
–
FCX u/c, with copper -2cents to $4.13
GOLD +1.1%
HOOD +3.3%
JACK -2.4%, post earnings cooling
MARA +10.2%
MCD -1.3%… to launch the ‘McValue’ $5 deal in 2025.
MSTR +10.9%
–
NET +2.6%
NVDA -0.8%, post earnings cooling
NVO -2.7%
OXY +0.5%
PANW -1.4%, post earnings cooling
–
PDD -8.4%, post earnings depression
SLB +0.5%
SMCI +2.4%
SNOW +21.6%, post earnings leap
UNG +3.9%, with Natgas surging to $3.41
–
VIX +1.0% at 16.51
–
XOM +0.5%, Goldman, 120>125
—
Overnight markets
Asian markets were mixed, whilst European markets are marginally higher…
Japan: -0.8% to 38036
China: +0.1% to 3370
Germany: currently +0.2% at 19044
UK: currently +0.3% at 8110
—
Have a good Thursday