Good morning. US equity futures are moderately lower, SPX -25pts, we’re set to open at 5828. USD is -0.1% at DXY 103.74. The precious metals are broadly higher, Gold +0.5% (printing $2753), with Silver +1.7% (printing $34.71). WTIC is +1.3% in the upper $70s.
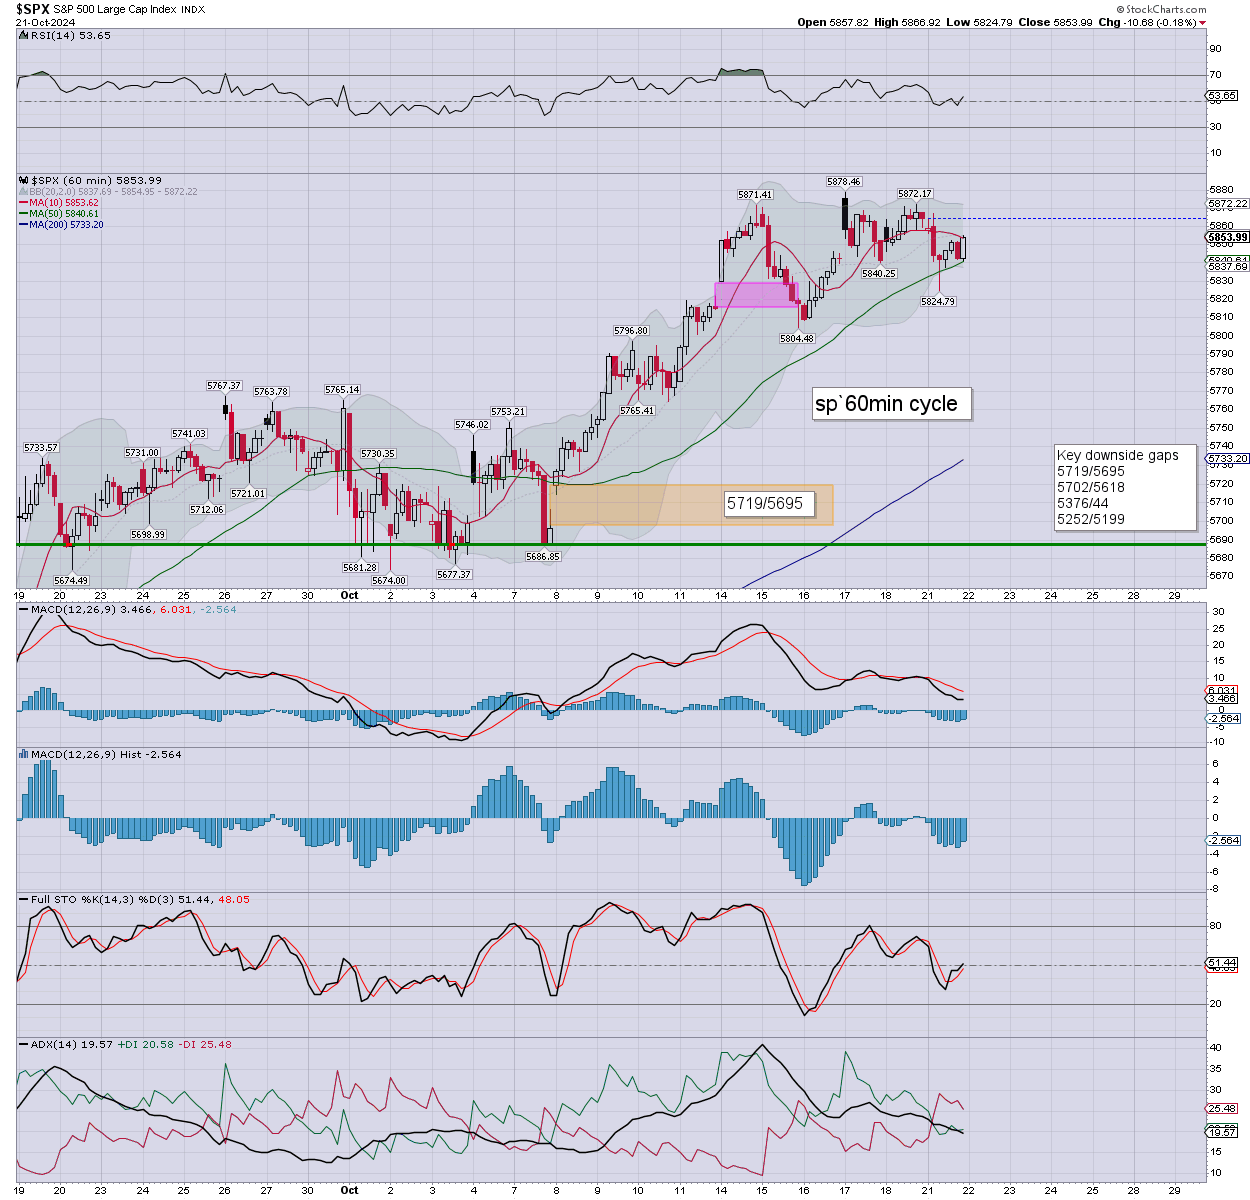
sp’60min
Summary
Yesterday saw early weakness, with a moderate latter day recovery. S/t momentum settled on the moderately low side.
Overnight futures have been leaning on the weaker side, pressured by most other world markets. Daily momentum will be prone to turning negative.
—
Early movers
AAPL -0.5%
AG +1.7%
ASML +1.3%
BABA -1.1%
CLF -1.4%
–
COIN -1.6%
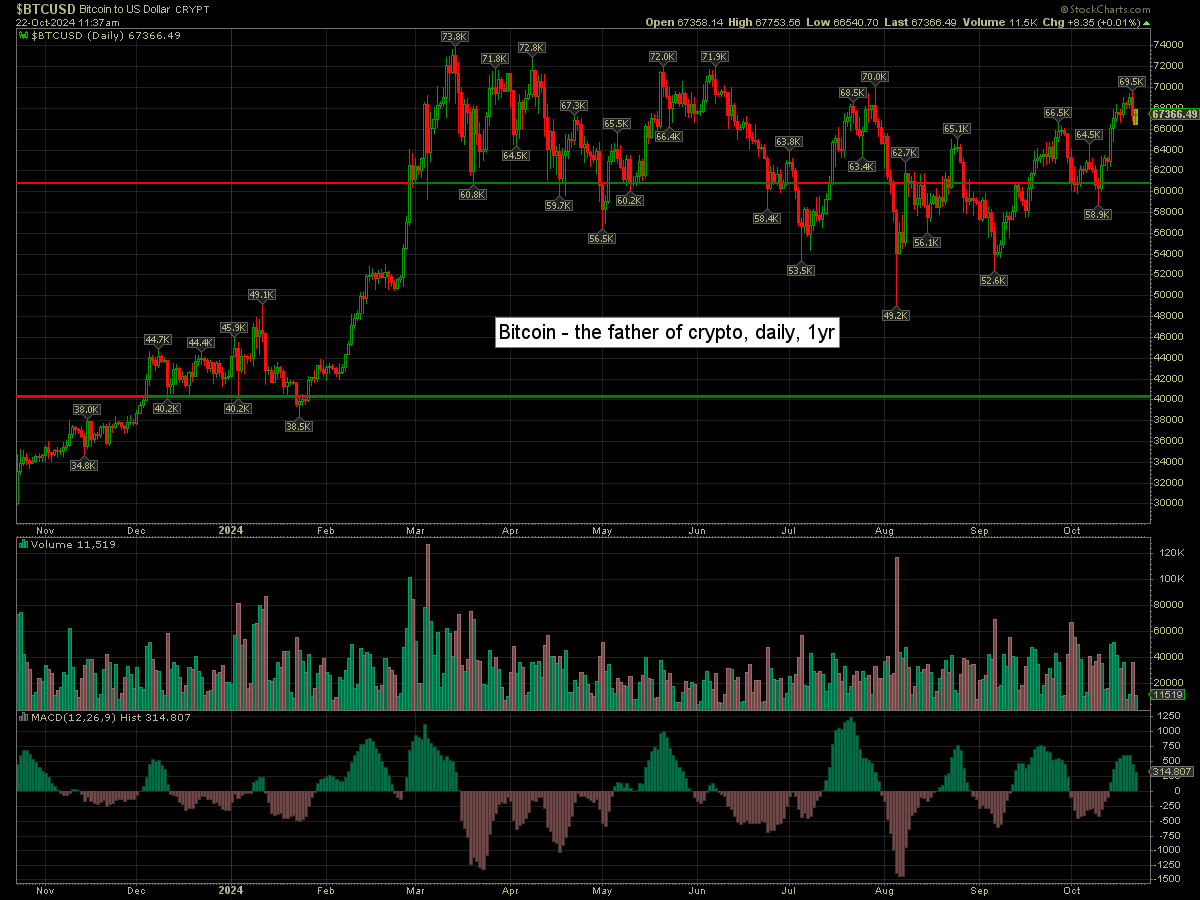
Bitcoin is +$8 at $67366
–
CSIQ -4.3%
DJT +2.1%, another day closer
EXK +3.3%
FCX +0.2%, with copper +4cents to $4.40
FSLR +1.8%
–
GE -4.2%, EPS $1.15 vs 1.14est. Rev’ y/y +5.8% to $9.8bn vs 9.4est.
–
GOLD +1.0%
–
GPC -9.1%, EPS $1.88 vs 2.42est. Rev’ y/y +2.5% to $5.97bn vs 5.94est.
–
HD -1.6%
IRTC +12.7%, FDA clearance for a medical device
–
LMT u/c, EPS $6.84 vs 6.50est. Rev’ y/y +1.3% to $17.1bn vs 17.3est.
–
LOGI -7.8%, post earnings depression
LOW -2.5%
–
MLI +9.7%, EPS $1.48. Rev’ y/y +21.7% to $997M vs 936est.
–
MMM +5.0%, EPS $1.98 vs 1.90est. Rev’ y/y -21.5% to $6.29bn vs 6.06est.
–
NEM +0.6%
–
NNE -8.7%
OKLO -1.8%
–
OXY +0.6%
PAAS +2.2%
PINS -2.4%
–
PM +2.6%, EPS $1.97 vs 1.82est. Rev’ y/y +8.4% to $9.9bn vs 9.7est. Philip Morris touting the ‘smoke free’ part of the business saw annual growth of 17%
–
RTX +1.7%, EPS $1.45 vs 1.34est. Rev’ y/y +6.0% to $20.1bn vs 19.8est.
–
SAP +3.5%, post earnings gains
SAVE -1.3%
–
SHW -8.1%, EPS $3.37 vs 3.54est. Rev’ y/y +0.7% to $6.16bn vs 6.20est.
–
SMR -1.4%
TSLA -0.6%
UAL -0.5%
UBER -1.2%
–
VIX +4.7% at 19.23
–
VZ -1.1%, EPS $1.19 vs 1.18est. Rev’ y/y u/c at $33.3bn vs 33.4est.
–
XOM +0.3%
—
Overnight markets
Asian markets were very mixed, whilst European markets are leaning weak…
Japan: -1.4% to 38411
China: +0.5% to 3285
Germany: currently -0.3% at 19397
UK: currently -0.7% at 8259
—
Have a good Tuesday