Good morning. US equity futures are a little higher, SPX +13pts, we’re set to open at 5854. USD is -0.2% at DXY 103.48. The precious metals are broadly higher, Gold +0.6% (breaking a new hist’ high of $2729), with Silver +1.1% (printing $32.37). WTIC is -0.5% in the upper $69s.
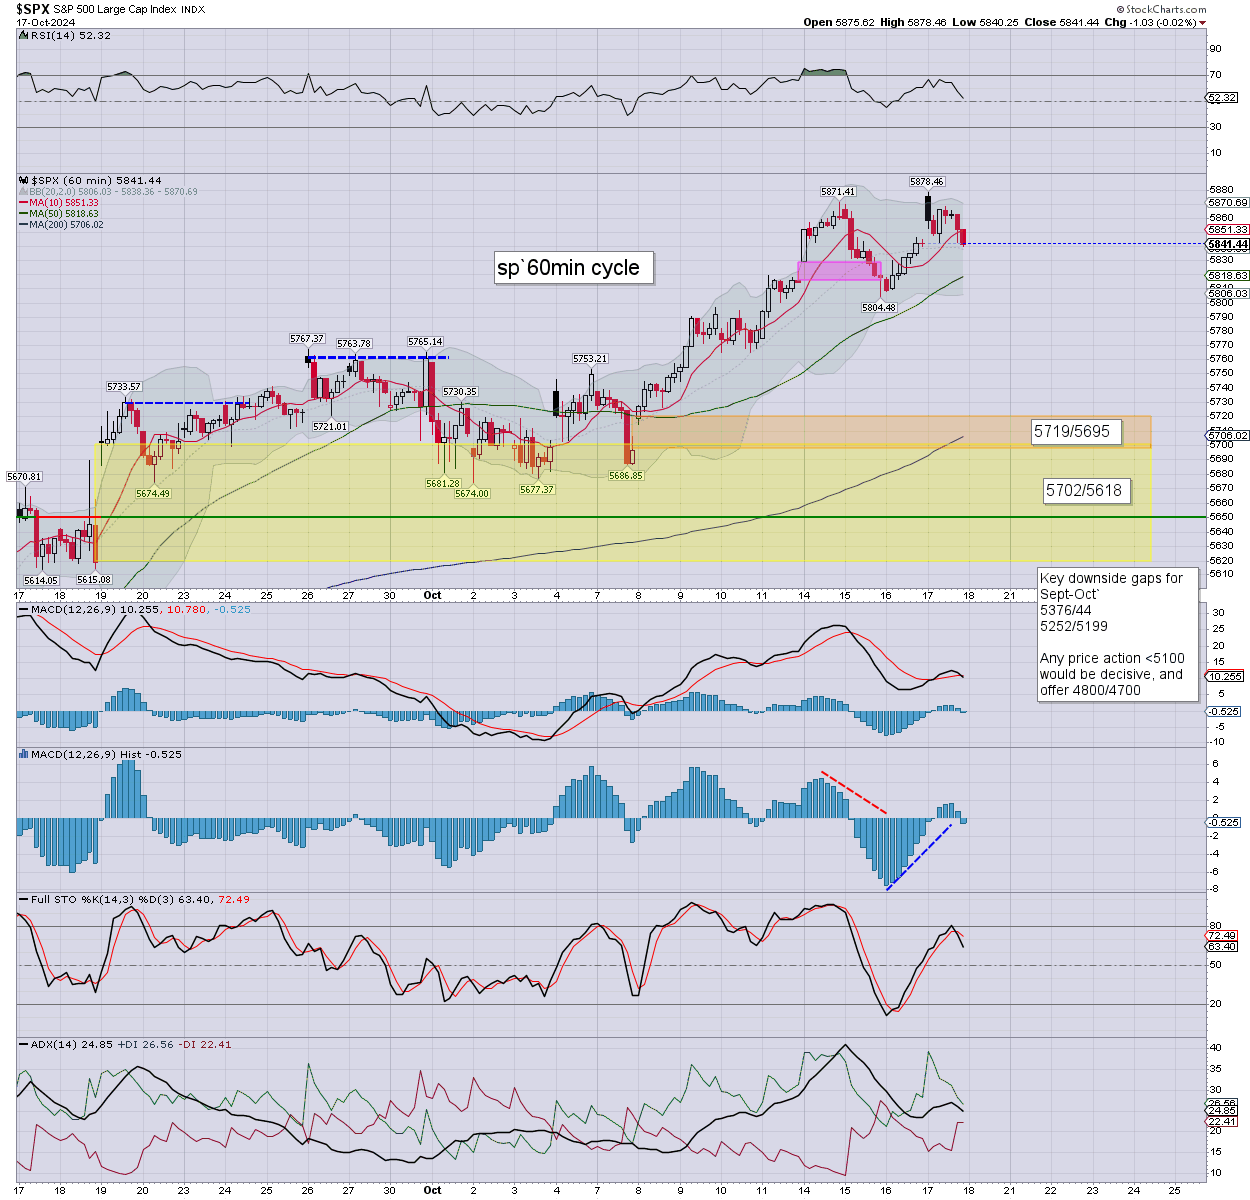
sp’60min
Summary
Yesterday saw the SPX, Dow, and NYSE comp’ break new hist’ highs. There was some latter day cooling, with the SPX turning fractionally red, and seeing hourly momentum turn negative.
Overnight futures have been leaning upward, especially helped by the rebounding Chinese market.
More than anything… keep in mind its OPEX. The market makers will try to work their magic, and pin the market around the nearest psy’ number. SPX 5900 looks unlikely. Instead… intermediate 5850… or 5800.
—
Early movers
AAPL +1.9%
AG +1.7%
–
ALLY +1.3%, EPS 95cents vs 53est. Rev’ y/y +1.1% to $2.06bn vs 2.03est. Fine.
–
AXP -1.7%, EPS $3.49 vs 3.28est. Rev’ y/y +8.0% to $16.63bn vs 16.66est. Broadly fine
–
BABA +2.8%, bouncing Chinese stocks
BIDU +3.7%
CCJ +0.6%
–
COIN +2.2%
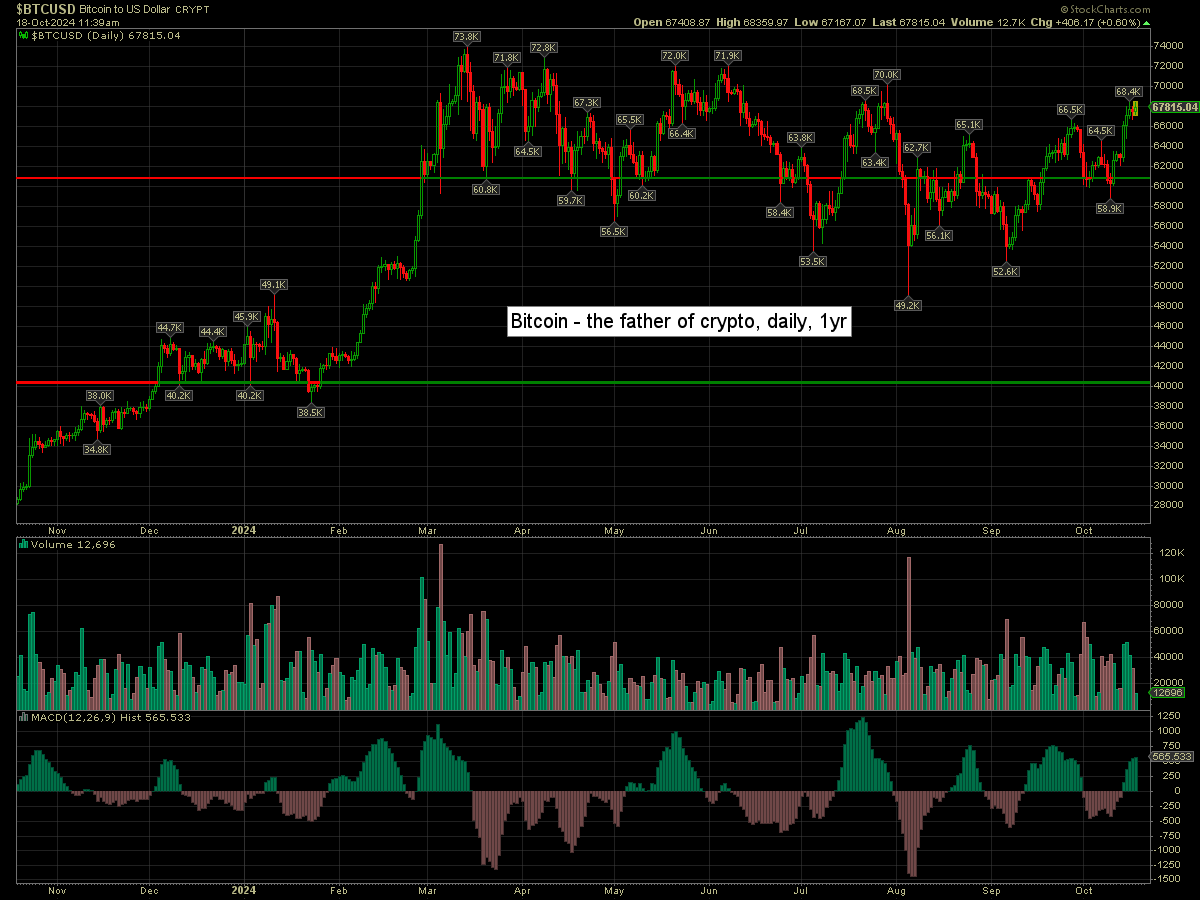
Bitcoin is +0.6% at $67815
–
CVS -12.2%, cuts guidance, new CEO
–
DDOG +3.1%, UBS, neutral>buy, 125>150
DJT -1.3%… another day closer.
–
FCX +1.6%, with copper +6cents to $4.38
GOLD +1.0%
ISRG +6.2%, post earnings jump
JD +5.1%
–
LVS +1.7%
NFLX +6.5%, post earnings jump
NIO +5.6%
NVDA +1.0%
OKLO -0.8%
–
PG -1.3%, EPS $1.93 vs 1.90est. Rev’ y/y -1.0% to $21.737bn vs 21.914est. The decline in annual sales should be a concern.
–
SLB -0.5%, EPS 89cents vs 88est. Rev’ y/y +10.2% to $9.16bn vs 9.25est. Broadly fine.
–
SMR -1.5%
STLA +2.5%
TSLA -0.5%… remaining s/t broken.
UEC +1.1%
–
VIX u/c at 19.11
–
WAL -3.1%, EPS $1.80 vs 1.89est. Rev’ y/y +14.9% to $823M vs 808est.
–
WBA -1.6%, in sympathy with sister CVS
WYNN +1.6%
—
Overnight markets
Asian markets were very mixed, whilst European markets are a little mixed…
Japan: +0.2% to 38981
China: +2.9% to 3261
Germany: currently +0.2% at 19626
UK: currently -0.3% at 8359
—
Have a good Friday