Good morning. US equity futures are fractionally higher, SPX +5pts, we’re set to open at 5820. USD is +0.02% at DXY 103.08. The precious metals are broadly higher, Gold +0.5%, with Silver +1.2%. WTIC is -0.7% in the low $70s.
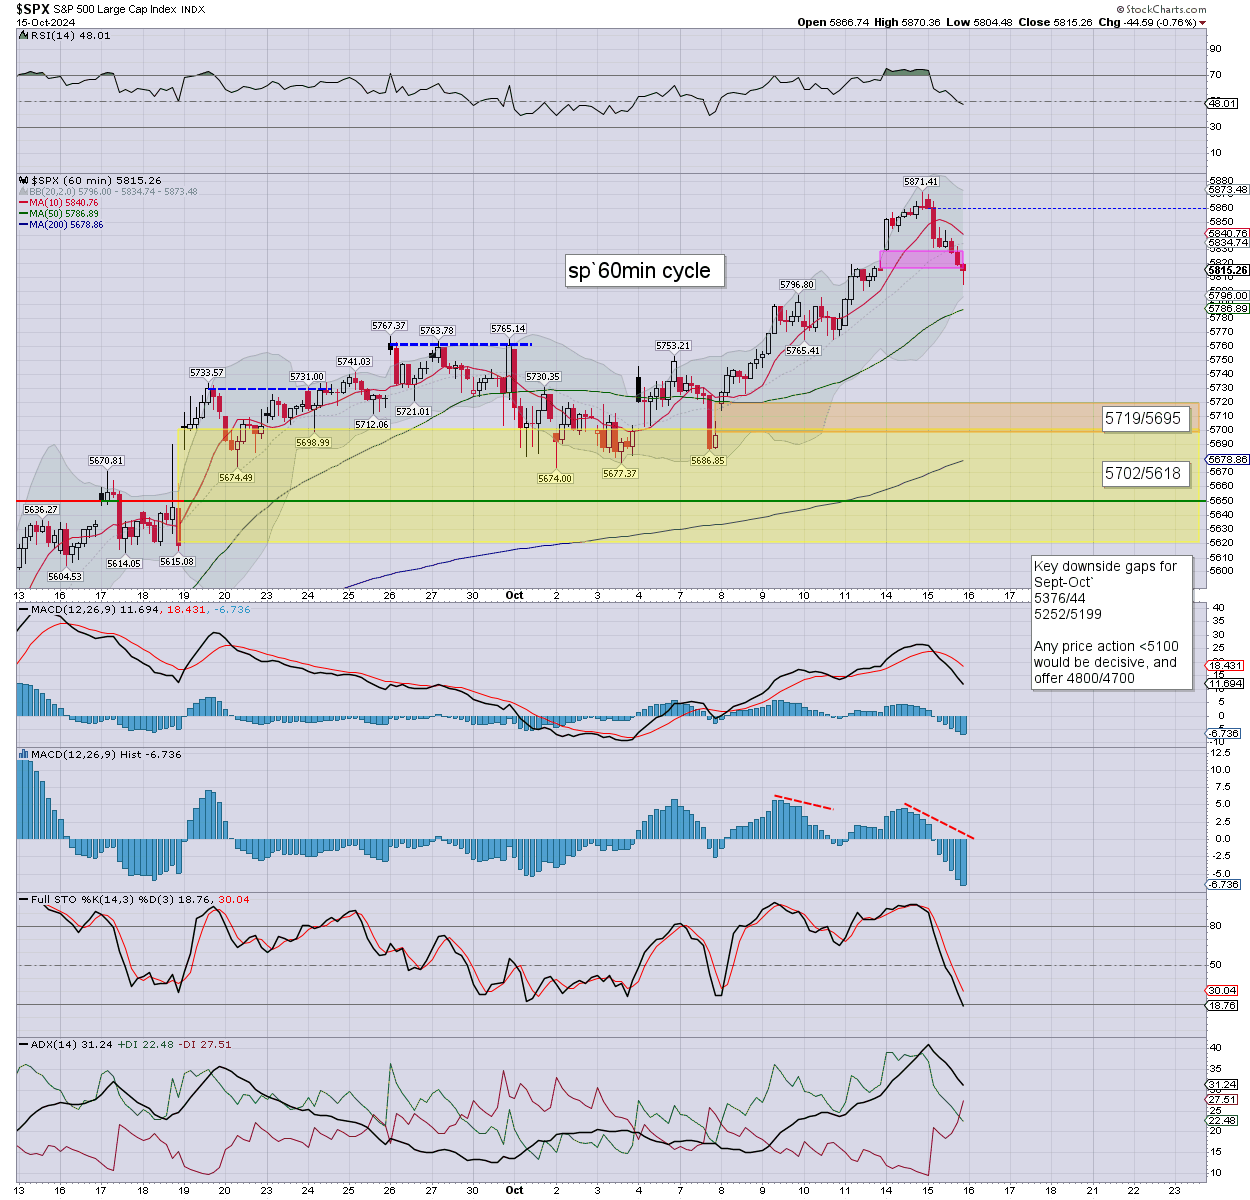
sp’60min
Summary
Yesterday saw the bulk of the market slide across the day… whilst the R2K was fractionally higher. S/t momentum settled on the very low side.
Overnight futures have been subdued, we’re set to open fractionally higher. The s/t cyclical setup favours the bulls.
Bears could look for a bear flag to form, with a stall from around the hourly 10MA (5840), with renewed sig’ downside on Thursday. I will continue to wonder if the market makers will be able to manage a pin around 5700 for Friday OPEX.
—
Early movers
AA +0.7%, earnings due in AH
AG +1.4%
AMD +0.7%
ASML -3.1%
CF -2.0%, BofA, underperform, $83
–
COIN +3.0%
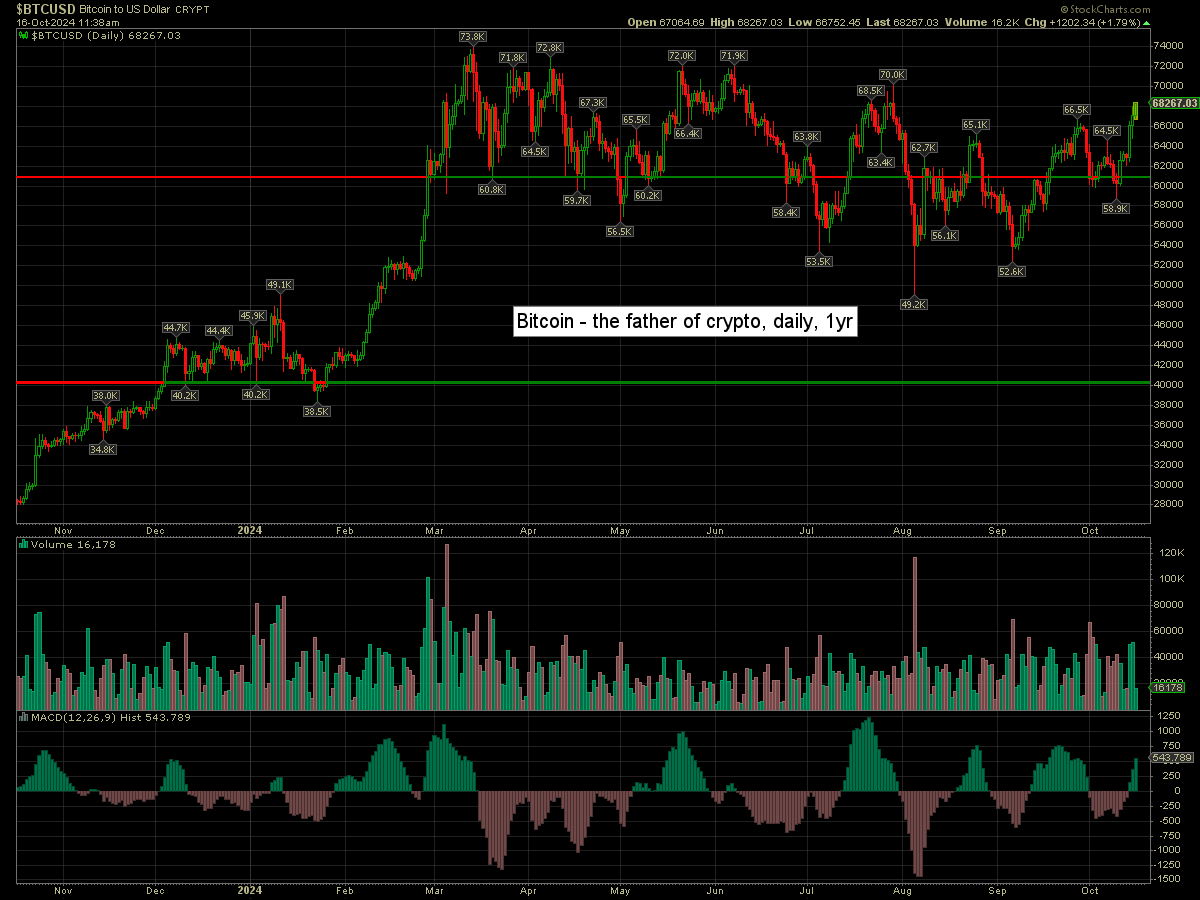
Bitcoin is +1.8% at $68267. Next resistance is psy’70K
–
CSCO +1.7%
DJT +4.7%
FCX +0.9%, with copper +5cents to $4.38
GFI +4.0%
GME -0.7%
GOLD +0.4%
–
IBKR -3.4%, post earnings depression
INTC -1.5%
JBHT +6.7%, post earnings jump
–
LAC +18.3%, partnership with General Motors to develop the Thacker Pass mine. GM will ‘contribute $625M in cash’
–
MARA +4.0%
–
MS +2.5%, EPS $1.88 vs 1.58est. Rev’ y/y +15.9% to $15.4bn vs 14.4est.
–
NEM +1.1%
NNE +3.1%, hot nuclear stocks
NVDA +0.8%
OKLO +0.9%
SMR +1.6%
SYF +5.1%, post earnings gains
–
TSLA +0.6%
UAL +1.2%, post earnings gains
UNG -0.8%, with Natgas $2.48
–
VIX +5.2% at 20.72
–
WBA -0.6%
—
Overnight markets
Asian markets were very mixed, whilst European markets are moderately mixed…
Japan: -1.8% to 39180
China: +0.05% to 3202
Germany: currently -0.2% to 19447
UK: currently +0.7% to 8304
—
Have a good Wednesday