Good morning. US equity futures are broadly flat, SPX +2pts, we’re set to open at 5471. USD is +0.3% at DXY 105.63. The precious metals are leaning weak, Gold -$12 (printing $2317), with Silver -0.2% (printing $28.70). WTIC is +0.7% in the $81s.
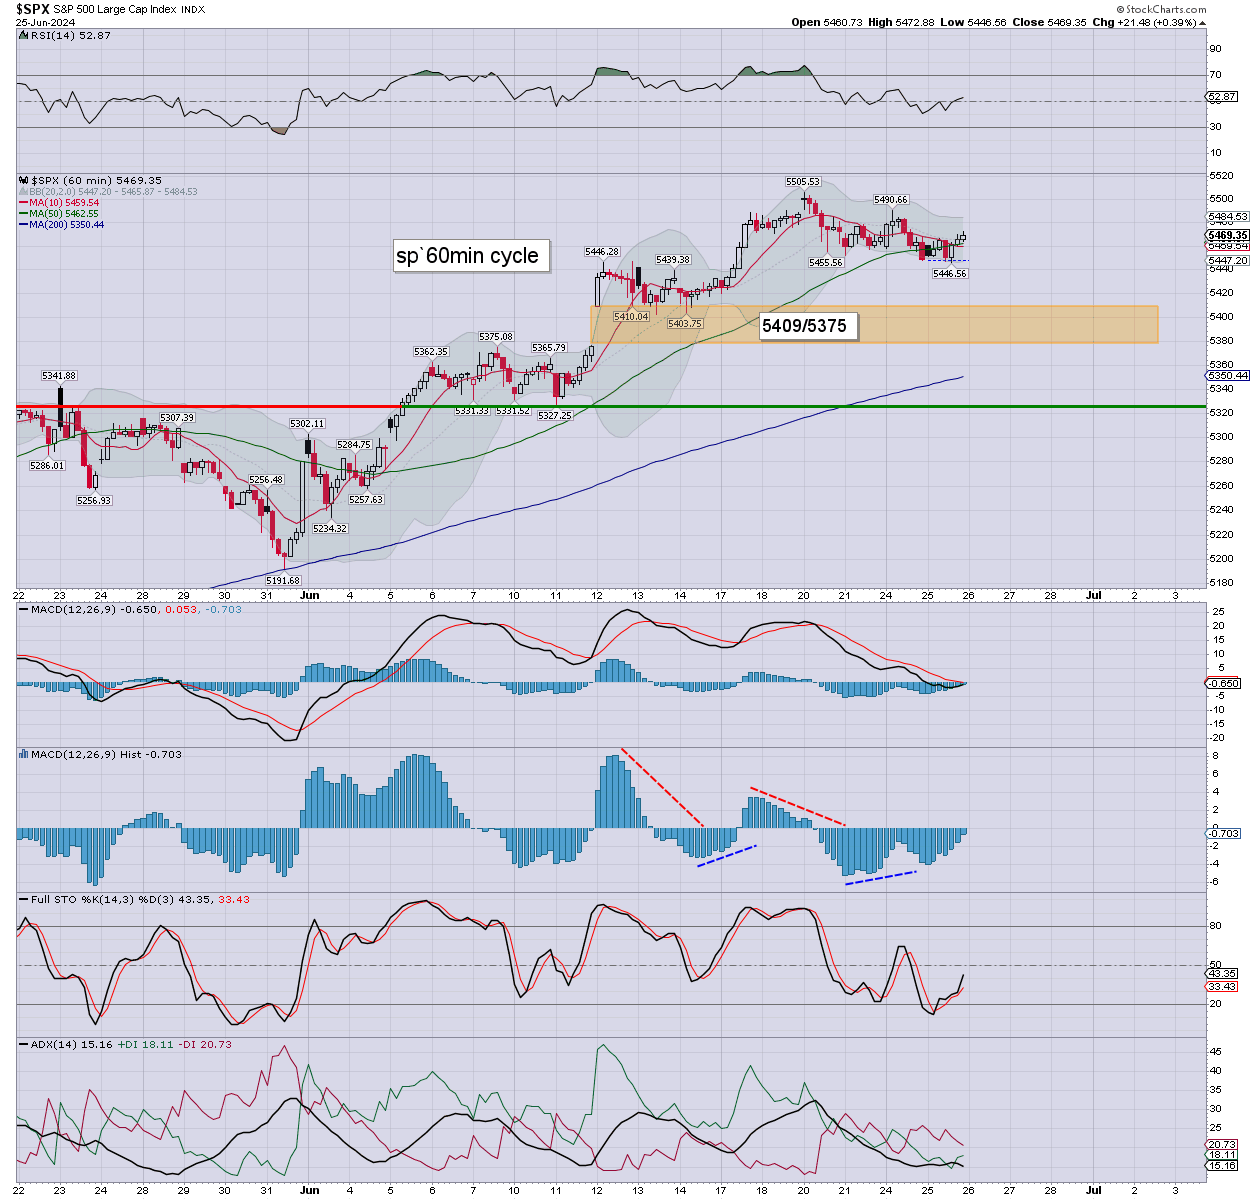
sp’60min
Summary
Yesterday saw considerable and pretty tedious minor chop, if settling moderately higher. S/t momentum settled marginally negative.
Overnight futures have been very subdued, we’re set to open broadly flat. The s/t cyclical setup favours the bulls, but I’d be open to a moderate cooling wave later today, and stretching into Thurs’.
There is little reason to expect anything other than broad chop until Q2 earnings, that formally begin July 12th.
—
Early movers
AAPL +0.9%, Rosenblatt, neutral>buy, 196>260
ALB +2.8%, plan for increased lithium auctions
AMC -1.1%
–
AMD +0.4%
CLF u/c, Morgan Stanley, 18.00>17.50
–
CMG -0.3%… in the $65s, with the 50 for 1 split.
–
COIN -0.6%
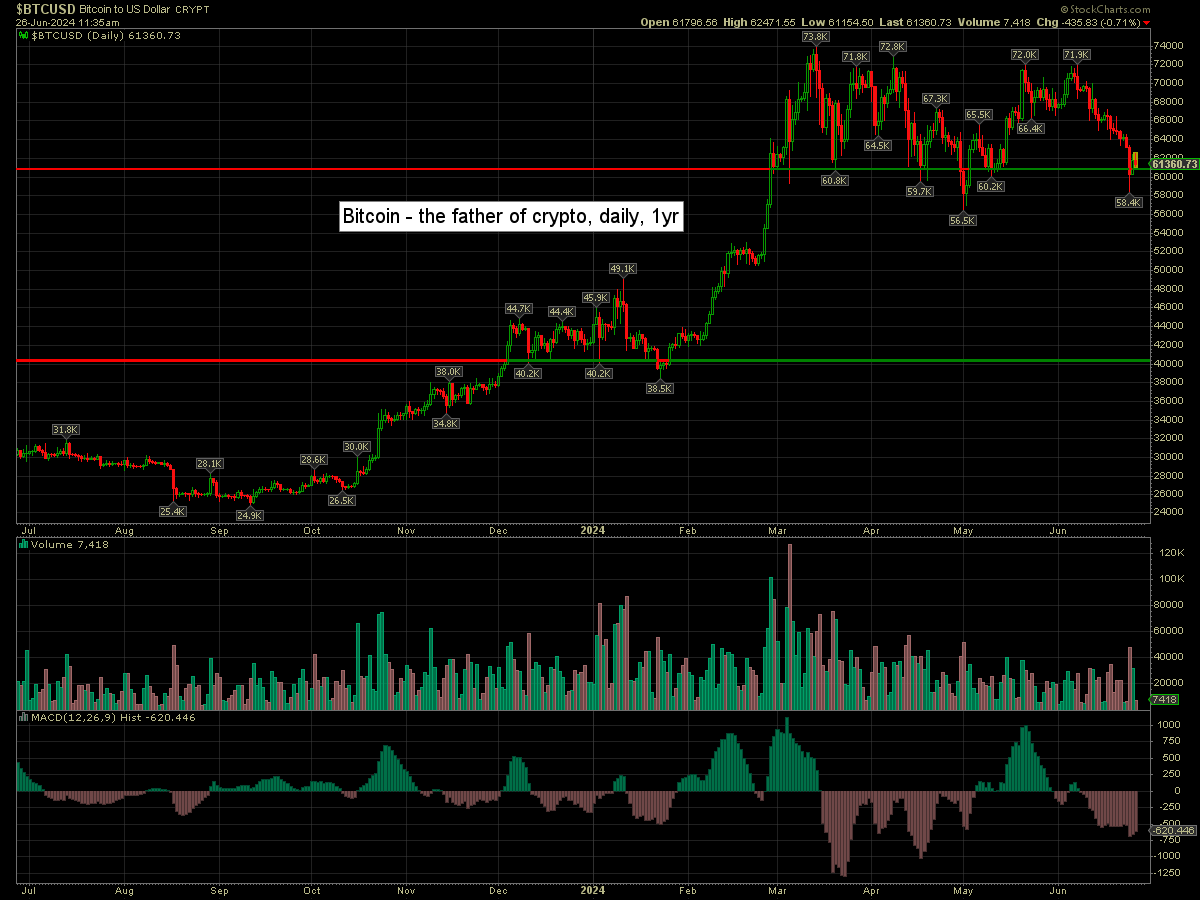
Bitcoin is -0.7% at $61360.
–
DJT -3.6%
ENVX +3.0%, MOU with battery pack manu’
–
FCX -0.1%, with copper -3cents to $4.34
–
FDX +13.6%, post earnings leap.
–
GILD -0.7% in the $69s, Redburn, 117>119
–
GIS -4.0%, EPS $1.01 vs 0.99est. Rev’ $4.7bn vs 4.9est. Weak guidance.
–
GME -1.8%
GOLD -0.4%
HD +0.6%, DA Davidson, buy, $395
HOOD +3.2%, Wolfe Res’, outperform, $29
–
LUV -3.0%, updated lowered guidance
–
MU +2.9%, earnings due in AH
NVDA +2.3%
–
RIVN +39.0%… in the mid $16s. VW of Germany to ‘invest’ $1bn before year end, and another $4bn for 2025-26. Rivian and VW will each hold 50% of a joint venture.
Wedbush, 15>20, Truist, 10>13
–
SHOP +1.7%
SMCI +0.7%
TLT -0.8%, as yields climb
UAL -0.4%
UPS +1.8%, helped by FDX
–
VIX +1.2% at 12.99
–
X +1.2%, BMO Capital, outperform, $45, which is bizarre, for a stock that is in limbo.
—
Overnight markets
Asian markets were broadly higher, whilst European markets are a little higher…
Japan: +1.3% to 39667
China: +0.8% to 2972
Germany: currently +0.2% at 18209
UK: currently +0.05% at 8251
—
Have a good Wednesday