Good morning. US equity futures are fractionally lower, SPX -11pts, we’re set to open at 6785. USD is -0.1% at DXY 98.34. The precious metals are mixed, Gold +2.1%, with Silver +0.1%. WTIC is +1.7% in the mid $60s.
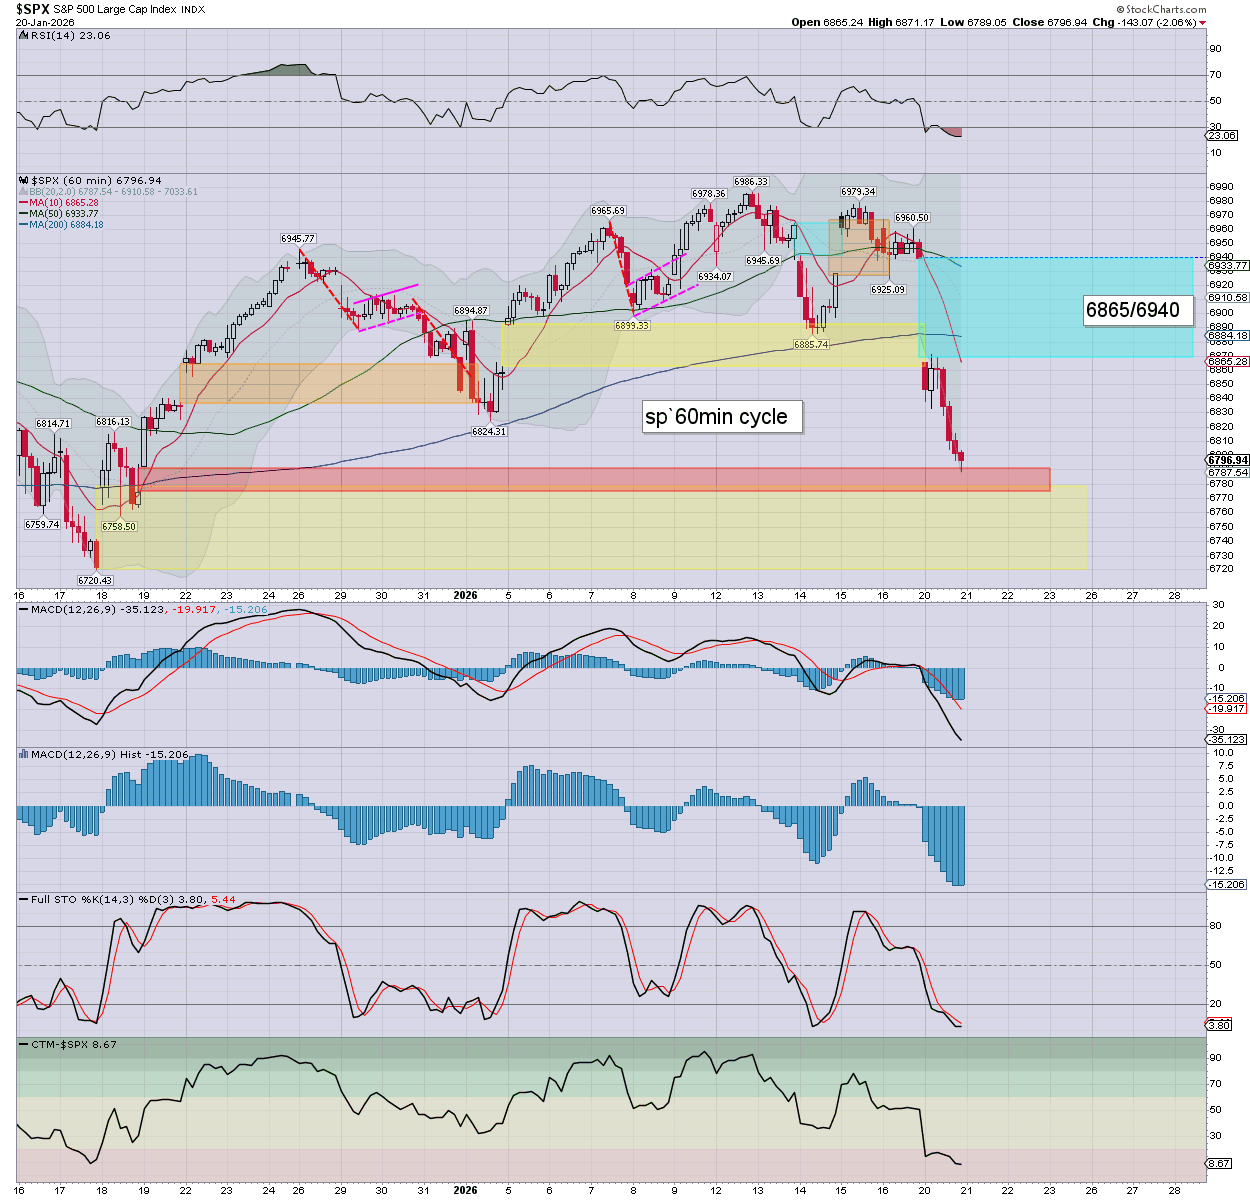
sp’60min
Summary
Yesterday saw very significant declines. S/t momentum settled on the very low side.
Overnight futures have been more stable… we’re set to open fractionally lower. The s/t cyclical setup favours the bulls, with basic upside target of teal gap.
—
Early movers
AAPL -0.2%
AEM +2.1%
AG +1.9%
–
ALLY -3.3%, EPS $1.09 vs 1.03est. Rev’ y/y +3.7% to $2.16bn vs 2.14est.
–
AMD +0.7%
BABA +2.8%
BIDU +5.1%
–
COIN -0.4%
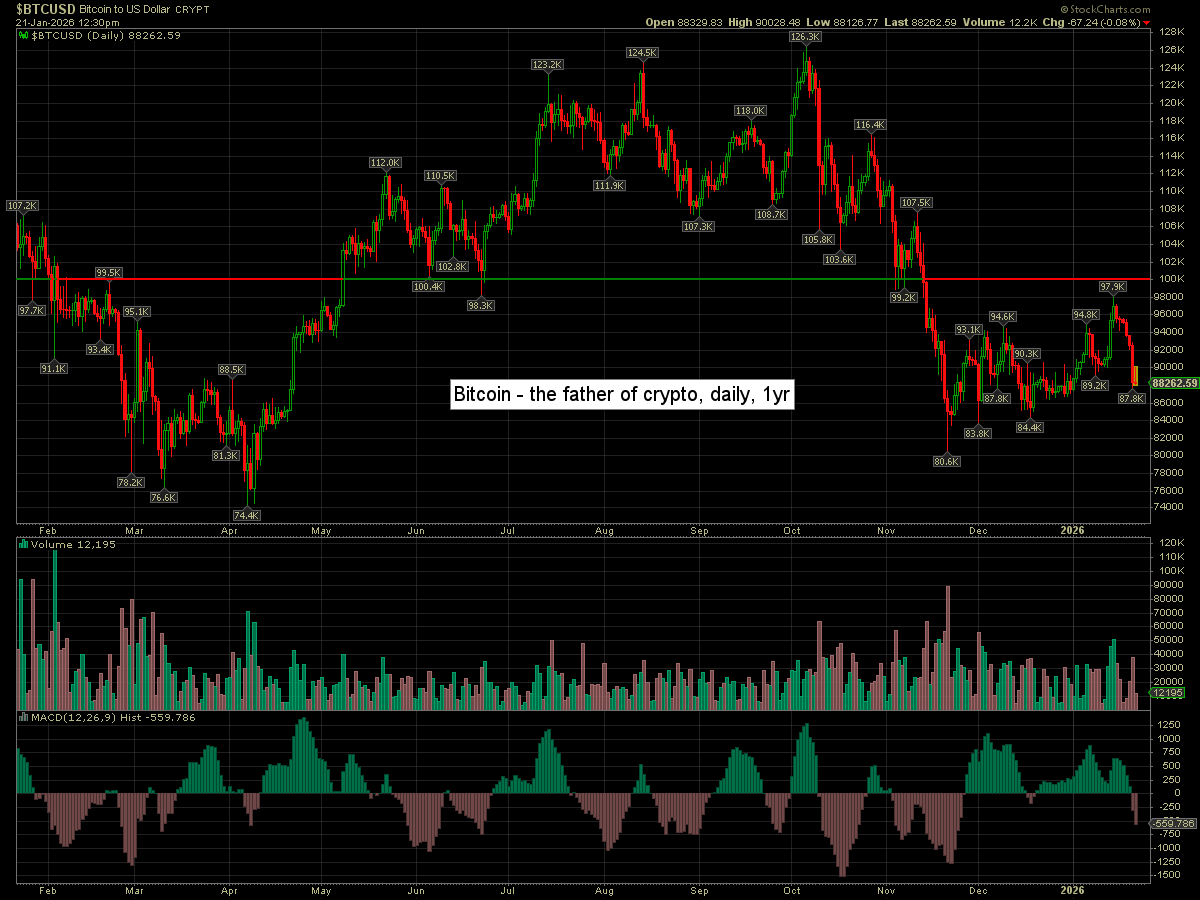
Bitcoin is -0.1% at $88K
–
FCX +1.6%, with copper +5cents to $5.86
GOOGL -0.9%
–
HAL +2.0%, EPS 69cents vs 55est. Rev’ y/y +0.8% to $5.65bn vs 5.41est.
–
INTC +2.4%
–
JNJ -1.4%, EPS $2.46 vs 2.44est. Rev’ y/y +9.1% to $24.56bn vs 24.16est.
–
KEP +6.3%, due to higher Natgas?
–
KHC -5.7%, chatter that Berkshire might sell stock
MU +2.1%
NEM +2.0%
–
NFLX -7.3%… post earnings depression, printing the $81s, taking out the April 2025 $82s. The door is open to full capitulation around $70.
–
NVO -1.4%
ONDS +3.7%
PAAS +1.8%
–
SCHW -1.5%, EPS $1.39 inline. Rev’ y/y +18.9% to $6.33bn vs 6.37est.
–
SMR +1.7%
UAL +3.2%, post earnings gains.
UNG +10.3%, with Natgas soaring to currently $4.66
–
VIX +1.4% at 20.37
–
XOM +0.6%
—
Overnight markets
Most markets are still leaning on the weaker side…
Japan: -0.4% to 52774
China: +0.1% to 4116
Germany: currently -1.1% at 24437
UK: currently -0.3% at 10094
—
Trump had a minor detour last night, but appears still due at the WEF this morning.
—
Have a good Wednesday