Good morning. US equity futures are moderately higher, SPX +35pts, we’re set to open at 6910. USD is -0.1% at DXY 98.50. The precious metals are mixed, Gold u/c, with Silver +0.7%. WTIC is -1.8% in the upper $59s.
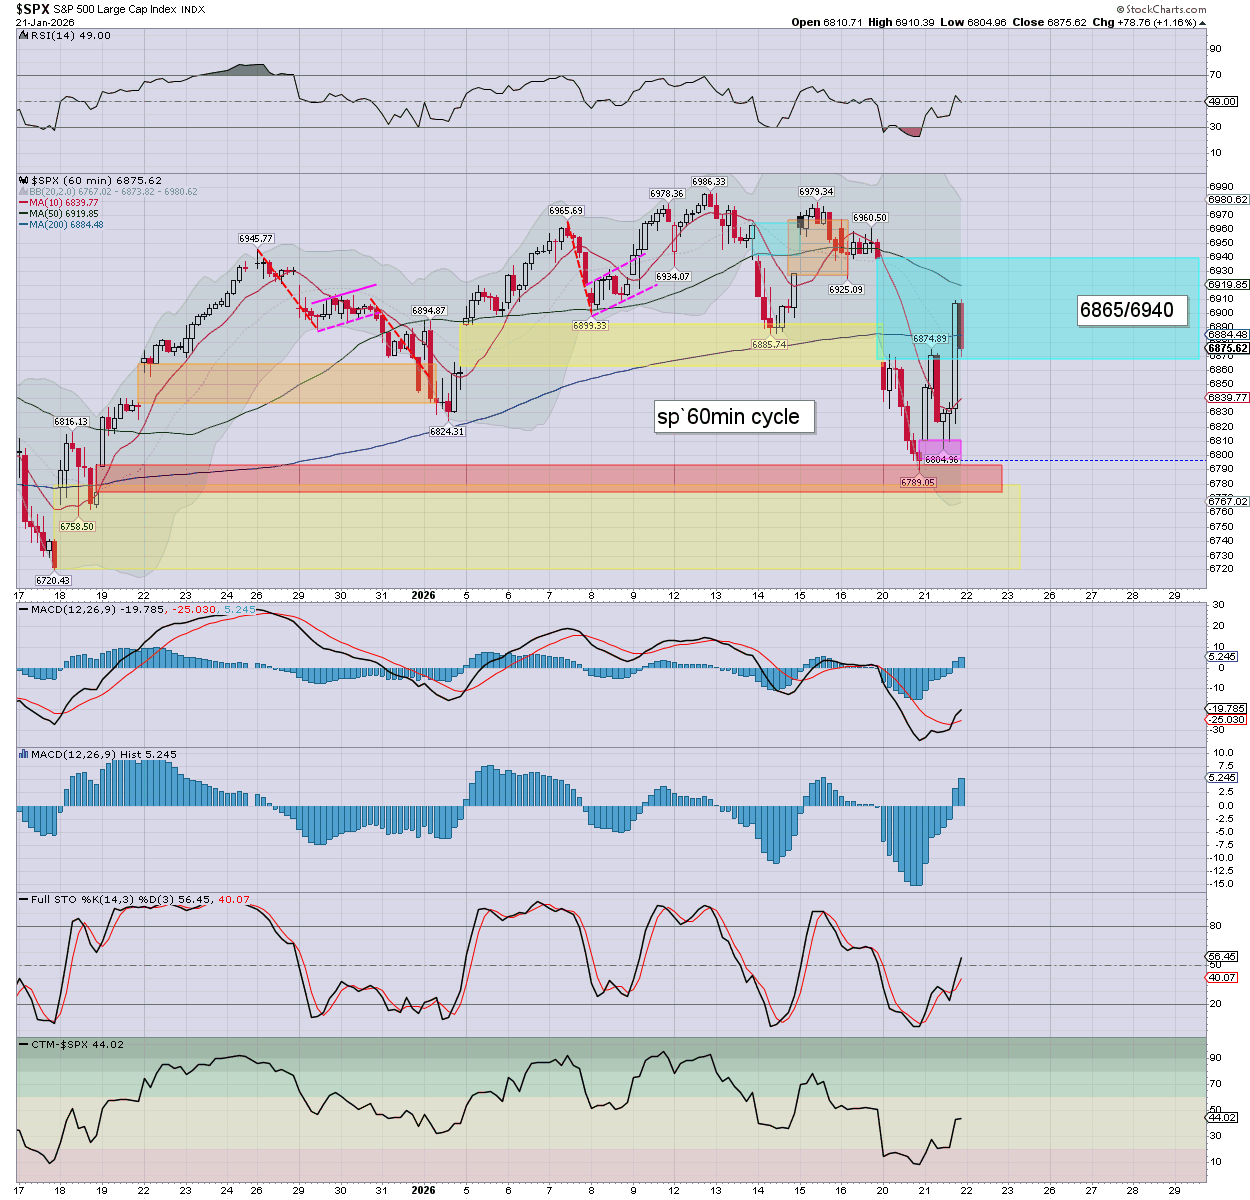
sp’60min
Summary
Yesterday saw a few swings… with Trump rescuing the market in the afternoon, to settle sig’ higher. S/t momentum settled on the moderately positive side.
Overnight futures have been leaning upward, we’re set to open +30pts or so… into the low 6900s.
S/t bulls should be hoping for teal gap to fully fill, with a weekly close >6944, which would make for a bullish engulfing weekly candle.
—
Early movers
AAPL +0.5%
–
ABT -4.9%, EPS $1.50 inline. Rev’ $11.46bn vs 11.80est.
–
ACHR +1.4%
AMD +1.9%
ASTS +3.0%, launch due – via Blue Origin, in late Feb
BABA +3.9%
_
BMY +0.3%
CAT +0.8%
CCJ +2.2%
CCL +1.6%
–
COIN +0.6%
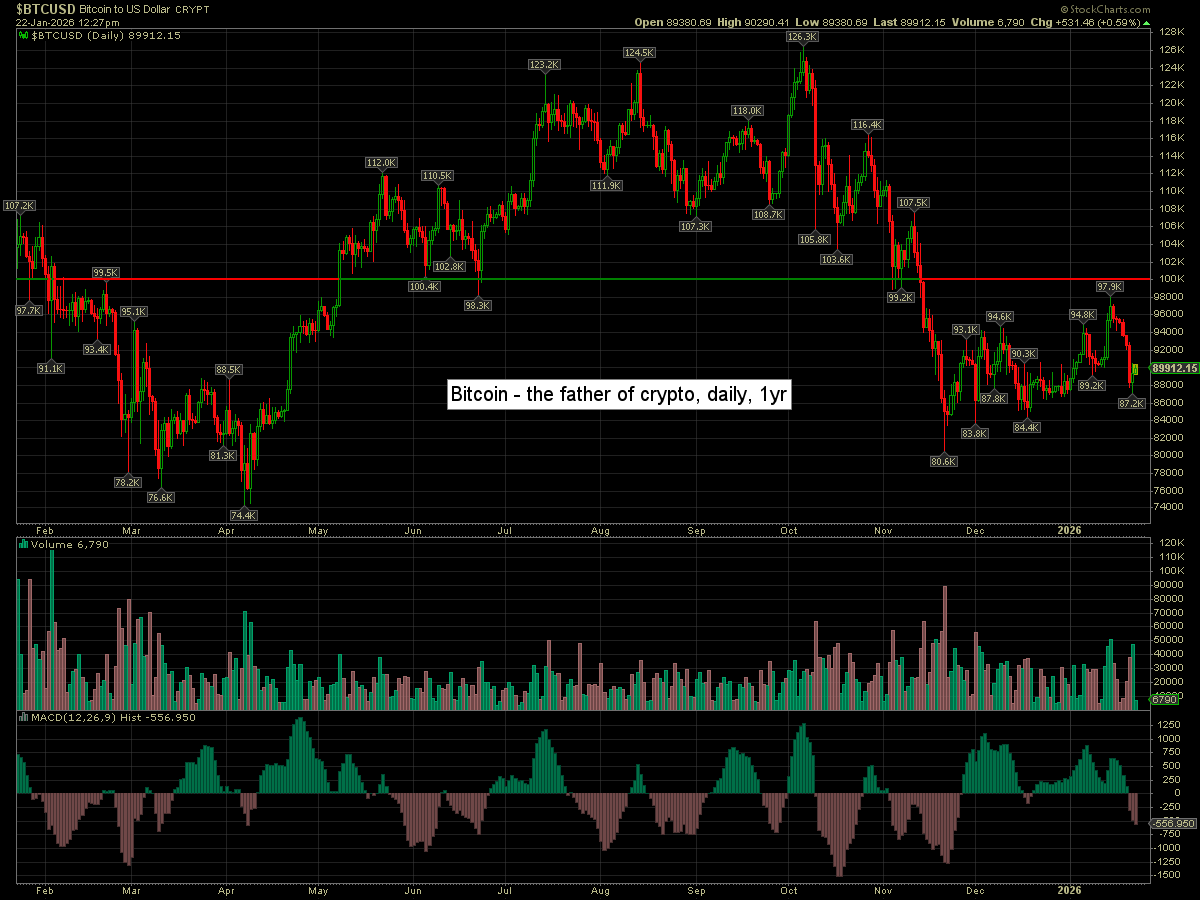
Bitcoin is +0.6% at $89K
–
FCX +0.4%, EPS *
–
GE -0.2%, EPS $1.57 vs 1.43est. Rev’ y/y +17.6% to $12.7bn vs 11.2est.
–
GOOGL +1.7%
INTC +1.2%, earnings due in AH
JOBY +1.5%
KNX -2.5%, post earnings depression
–
KRMN +7.9%, updated guidance. Piper Sandler, neutral, $98
META +1.6%
MP +1.2%
–
MRNA +4.8%, bullish chatter about a cancer vaccine. The irony.
MU +2.1%
NVDA +0.9%
–
OKLO +2.8%
OXY -0.4%
PAAS +0.3%
–
PG -1.8%, EPS $1.88 vs 1.86est. Rev’ y/y +1.5% to $22.2bn vs 22.3est.
–
PLTR +1.6%
QBTS +2.1%
–
RKLB -1.7%
SMR +2.7%
SNAP +4.1%
TSLA +1.1%
UNG +4.2%, with Natgas soaring to $5.47
–
VIX -4.3% at 16.17
–
XOM -0.9%
—
Overnight markets
Asian and European markets all leaning upward…
Japan: +1.7% to 53688
China: +0.1% to 4122
Germany: currently +1.1% at 24832
UK: currently +0.2% at 10156
—
Have a good Thursday