Good morning. US equity futures are broadly flat, SPX +3pts, we’re set to open at 7726. USD is +0.1% at DXY 99.63. The precious metals are moderately mixed, Gold +0.3%, with Silver -0.4%. WTIC is +0.8% at $75.85.
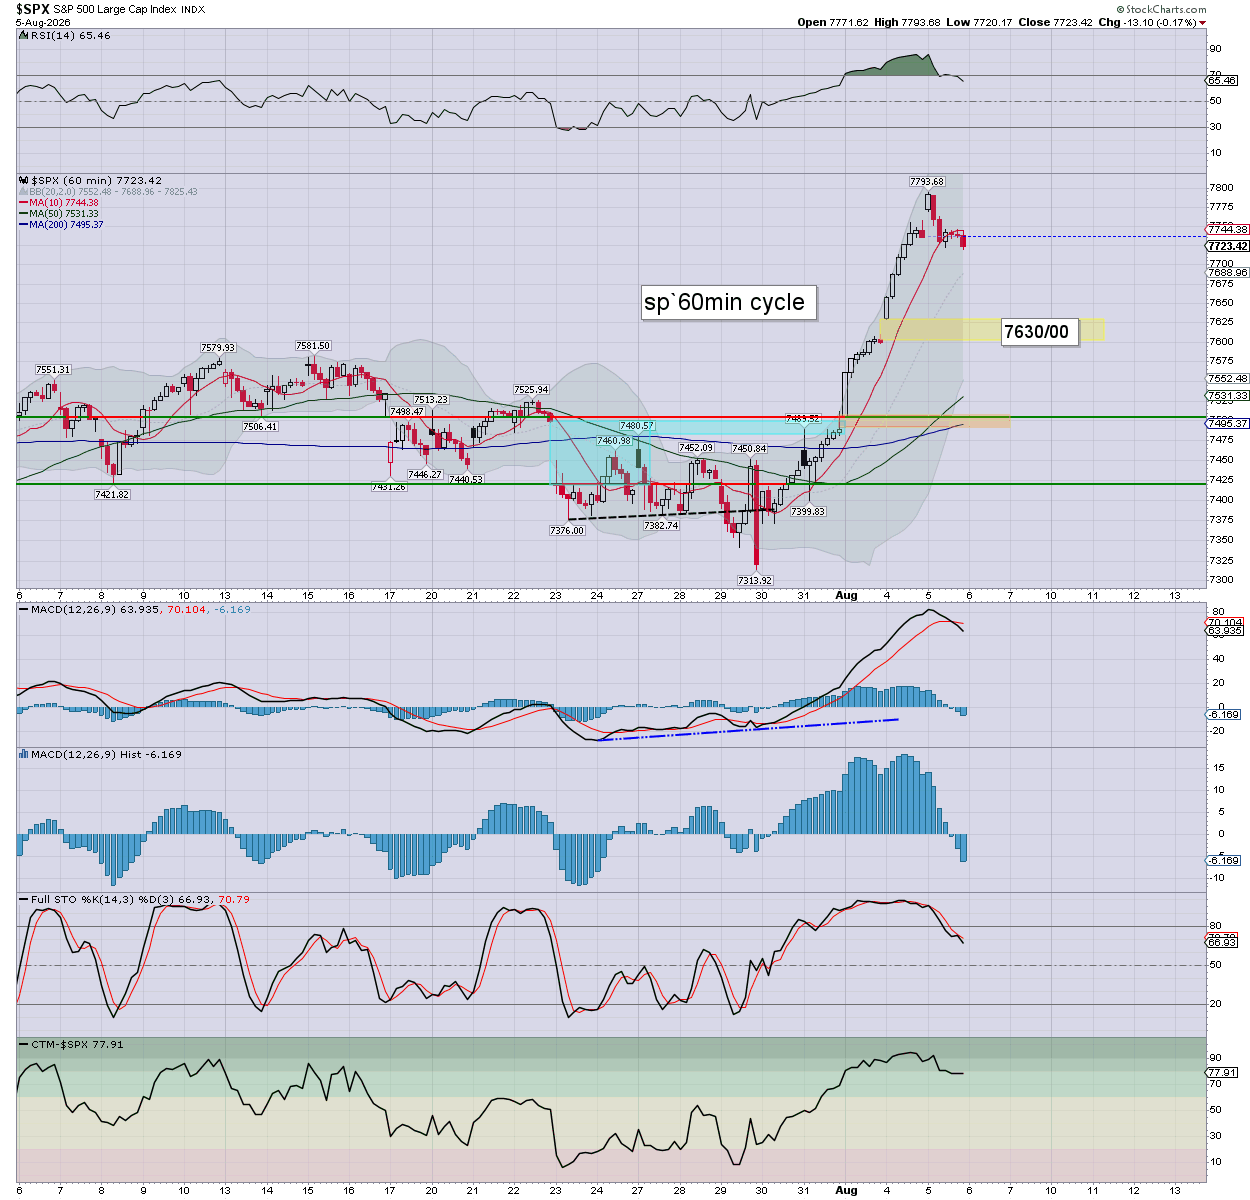
sp’60min
WTIC, daily
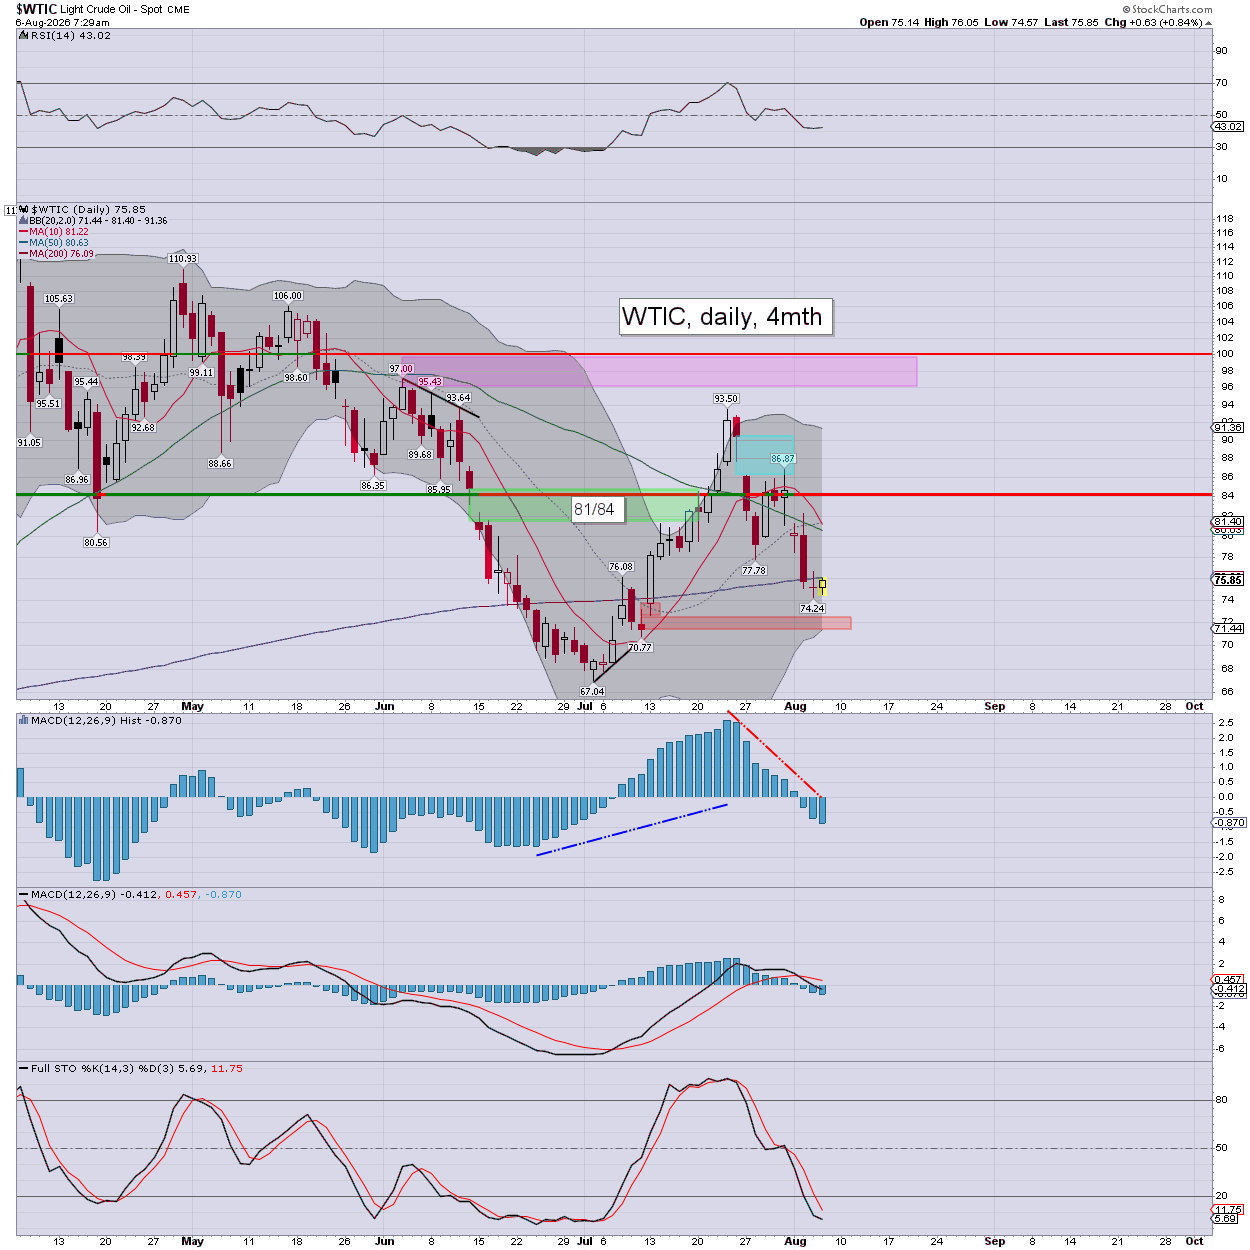
Daily momentum is increasingly negative, as a more natural low would be the remainder of red gap, 72/71s.
–
Summary
Yesterday saw the SPX break a new hist’ high of 7793, if cooling back to settle marginally lower at 7723. S/t momentum weakened across the day, settling on the moderately low side.
Overnight futures have been subdued, we’re set to open fractionally higher. Its a Thursday, and we should expect to see some downside today. I’d be open to the mid/low 7600s.
I wish I could believe in Mr Burry’s crashy scenario. The good thing… those things don’t just occur out of nowhere. There are pre-cursor patterns/structure to look for. In any case… I’ll be looking for a market washout low (if only 10%) within mid Oct/early Nov’.
Ohh, and to be clear, I’m still broadly with the Tom Lee, and expect a very strong 2027. SPX 10K… with the US 10yr yield around 7%, would be ideal.
—
Early movers
AAPL +1.0%
AEM +0.6%
AMD -0.4%
AMZN +0.5%
APP -19.1%, post earnings horror
–
BAC +0.7%, set for yet another new hist’ high
–
BROS -10.3%, post earnings upset
–
CDE -3.4%, EPS 12cents vs 32est. Rev’ y/y +125.8% to $1.08bn vs 1.28est.
–
CELH -16.6%, EPS 36cents vs 42est. Rev’ +10.6% to $817M vs 870est
–
CF -5.7%, EPS $4.73 vs 5.44est. Rev’ y/y +17.6% to $2.22bn vs 2.43est.
–
COIN u/c
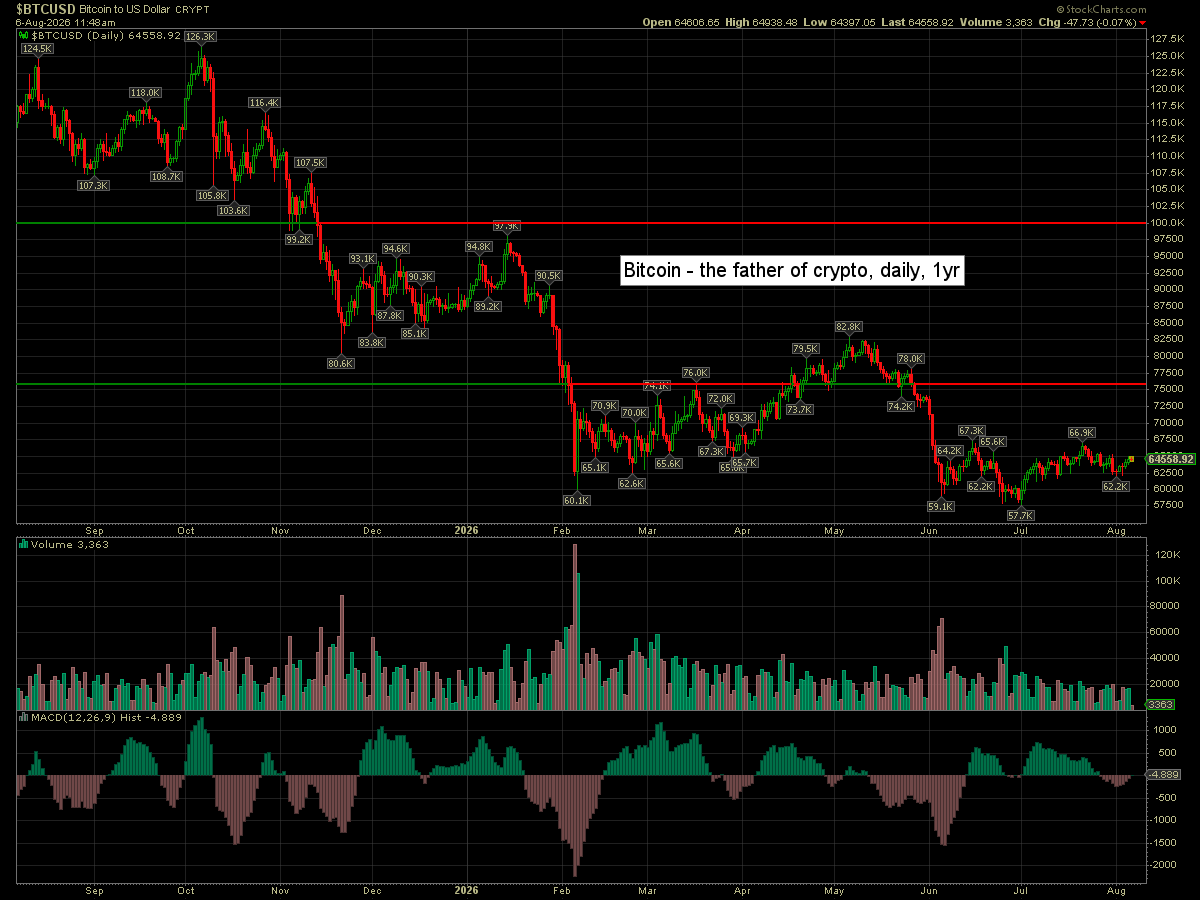
Bitcoin is -0.1% at $64K
–
CRM -4.7%, new Operating Chief… Mr Milano
DASH +3.7%, post earnings gains
–
DDOG -21.0%, EPS 65cents vs 59est. Rev’ y/y +35.6% to $1.12bn vs 1.08est. Positive guidance… but the market still smashes this lower.
–
DEO +7.5%, EPS $1.65 vs 1.64 prior yr. Rev’ y/y -3.0% to $19.64bn vs 20.25 prior yr.
–
DIS +0.6%
FIG -14.0%, post earnings horror
–
HONA -14.8%, EPS $1.87 vs 2.75 prior yr. Rev’ y/y +5.4% to $4.52bn vs 4.28 prior yr. Honeywell Aerospace warning about ‘supply constraints’
–
HUBS -22.9%, EPS $3.26 vs 3.02est. Rev’ y/y +19.8% to $912M vs 898est. Guidance cut.
–
INTC -1.1%
JPM +0.8%
–
MRNA +3.9%, FDA approve mFLUSIVA… the first mRNA based flu gene therapy shot. Last night saw a new director of the CDC, who recently touted ‘mRNA technology as safe and effective’.
I’m well aware at the fury and betrayal felt by many of red team.
Another reminder that if voting mattered… they’d not allow it.
–
MSFT -0.8%
MU -4.4%
NVDA +1.0%
OXY +1.7%
PLTR -1.7%
–
PTON -12.7%, EPS 13cents vs 12est. Rev’ y/y +0.2% at $608M vs 597est.
–
QBTS -11.7%, EPS -13cents vs -10est. Rev’ y/y -0.6% to $3.07M (millions… not billions!) vs 4.02est. Micro cap… the cautious will leave alone.
–
RCAT +0.7%, earnings due in AH
RKLB -0.7%
SMR -3.7%
–
SNDK -9.4%, EPS $39.25 vs 34.45est. Rev’ y/y +371.6% to $8.96bn vs 8.39est.
–
SNOW -6.1%
–
SOUN +25.8%, EPS -2cents vs -6est. Rev’ y/y +45.0% to $61.9M vs 52.4est.
–
SPCX +3.1%
–
TAP +1.0%, EPS $1.58 vs 1.51est. Rev’ y/y -3.2% to $3.09bn vs 3.08est. Molson Coors citing ‘demand challenges and supply costs’.
–
TRIP -2.8%, EPS 35cents vs 37est. Rev’ y/y -16.5% to $441M vs 503est.
–
U +14.0%, EPS 28cents vs -9est. Rev’ y/y +23.9% to $546M vs 514.6est.
–
USFD +3.5%, EPS $1.44 vs 1.36est. Rev’ y/y +4.5% to $10.5bn vs 10.5est.
–
VIX +0.9% at 15.96
–
WDC -14.5%, EPS $3.56 vs 3.29est. Rev’ y/y +43.8% to $3.74bn vs 3.69est.
–
XOM +1.0%
–
Z -10.2%, EPS 52cents vs 45est. Rev’ y/y +17.9% to $772M vs 758est. Market annoyed on ‘restructuring costs’
—
Overnight markets
Asian markets were very mixed… with South Korea getting whacked. European markets are a little higher.
Japan: -0.9% to 65683
China: +0.6% to 3900
South Korea: -4.6% to 6296
–
Germany: currently +0.1% at 26164
France: currently +0.6% at 8724
UK: currently +0.1% at 10901
—
Yours truly awoke at 6am, with a racing mind… as I’m filled with ideas, as I battle for mid/long term survival. I’m swinging from moments of hope to abject despair. Its… not easy, and frankly, I’ve no business hitting buttons in my current psychological state.
Have a good Thursday